
The Problem: Your Spend Lives in Three Places
Your dealership manages spend across three disconnected systems: a card program from your bank, vendor payments keyed through the DMS, and employee reimbursements processed by hand. None of them share approval rules, and none of them integrate to accounting in real-time. Meanwhile, the operating cash that funds all of it sits in a checking account earning little or nothing.
By month-end, your controller is buried in reconciliation: matching card statements to DMS entries, chasing vendor payments, figuring out what cleared and what didn't. Three systems. Three statements. Three manual processes.
The real cost isn't just your controller's time. It's the miscoded expenses that slip through, the spend nobody approved before it happened, and a cash position nobody can see until the statement arrives.
What Is Tekion Spend?
Tekion Spend is a unified spend-management platform built directly into Tekion’s Automotive Retail Cloud (ARC), where your DMS, CRM, and accounting already live.
With Tekion Spend, your dealership gets a business deposit account held at Core Bank, Member FDIC, and a 30-day charge card provided through Brex. Every payment, swipe, and approval shows up in accounting in real time, inside the same system that already runs your dealership.
Tekion Spend brings three things together:
1. Vendor Payments with Automatic Reconciliation
Pay every vendor bill directly from ARC via ACH (next-day or same-day), RTP (real-time payment), paper check, or card. Your AP team chooses the payment rail for each vendor, so you pay for speed only when you need it. For vendors that accept card, Tekion Spend generates a single-use virtual card: your dealership earns cash back and keeps its cash until the 30-day statement comes due. The moment a vendor payment leaves your account, it shows up in Accounting automatically. No spreadsheets, no waiting, and no chasing down what got paid and when.
2. Business Deposit Account with a Deposit Bonus
Every dealership gets a business deposit account, held at Core Bank, Member FDIC, that pays a deposit bonus on the cash sitting in it. No minimum balance is required. Balances are eligible for FDIC insurance up to applicable limits through Core Bank's network of program banks.* The deposit bonus is variable and currently pays up to 2.00% annualized, depending on your balance,* so your operating cash earns something instead of sitting idle.
3. Corporate Charge Card
Issue cards for every kind of spend, all from inside ARC. Alongside one-time-use cards that work for a single purchase and then expire, you can issue employee cards, physical and virtual, for everyday spending, and recurring virtual vendor cards, uniquely-generated to a specific vendor, for subscriptions and repeat bills. Built-in controls set each card's limit and the merchant categories where it works, before anyone swipes. It's a charge card, so there's no prefunding: the balance is due in full every 30 days. Your dealership earns cash back on every transaction. And because employees spend on a company card instead of their own, out-of-pocket reimbursements largely go away.
Your Revenue Funds Your Payables
If you process payments on Tekion Pay, your settlements can deposit into your Tekion Spend account every day. That same balance earns the deposit bonus, pays your vendors, and pays off your card, all without leaving ARC.
Money comes in from customers, sits in an account that pays you, and goes out to vendors, with every step posted to accounting. A standalone AP tool or card program can't close that loop, because it doesn't sit where your revenue lands.
What Makes Tekion Spend Different?
Most spend tools sit outside your DMS and connect through an API or a nightly file sync. That's where things break: sync delays, GL mappings that drift, duplicate vendor records, a second login, and a second set of approval rules to maintain. Tekion Spend is built directly into ARC, so bill pay, cards, and deposits all run inside the same system your accounting team already uses.
Because Tekion Spend posts natively to the ARC general ledger, a payment and a GL entry are the same event, not two separate processes. When a vendor payment leaves, it flows to accounting in real time, every time. When an employee swipes a card, the charge can automatically maps to the right expense account. You define.
Here's what that means operationally:
For your controller: You see exactly when a bill was approved, who approved it, and how it was paid, all inside your accounting system of record. Month-end reconciliation is simplified because every transaction is already in your books where it belongs. Your close shifts from matching three systems to reviewing and validating what's already there.
For your dealer principal: You see and control spend across every rooftop in real time, instead of discovering what happened on the statement a month later. Set approval rules and controls, and the system enforces them automatically.
For your employees: Swipe, snap a receipt on your phone, done. No expense reports, no waiting to be reimbursed. Card controls define what's allowed before the swipe, so there's no guessing about approval.
Pairing Tekion Spend with Accounts Payable AI
Tekion Spend handles outbound payments and Accounts Payable AI handles inbound invoices, all inside ARC, covering the full cycle from invoice to payment.
When an invoice arrives in email, Accounts Payable AI captures it, extracts key fields, and automatically codes it to the right GL account, either by matching a PO or by using the vendor's default account. Once approved through your configured approval rules, payment leaves through Tekion Spend and posts to the GL in real time.
The Result: A Faster, Cleaner Close
Tekion Spend turns bill pay, corporate card spend, and deposits from three disconnected systems into one workflow inside ARC.
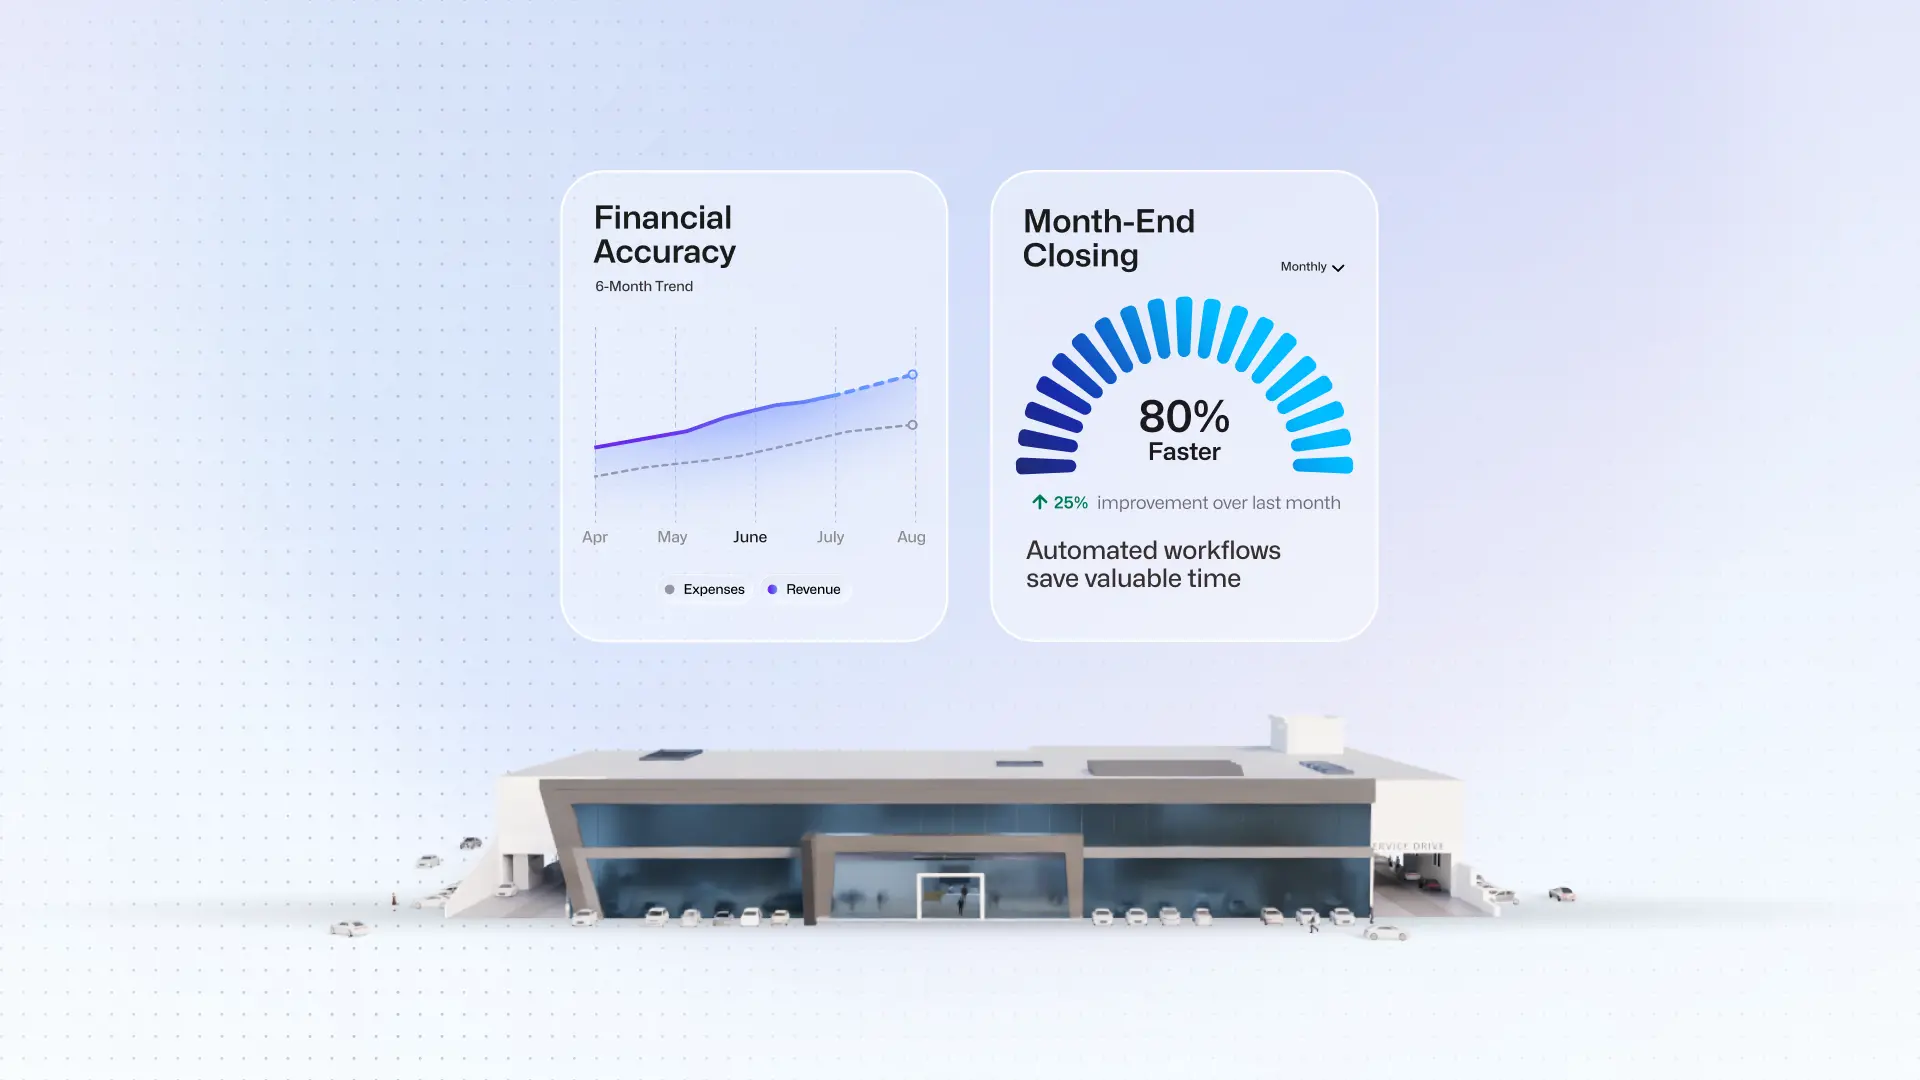
For dealers managing their spend across separate platforms today, real-time GL posting changes what month-end looks like. Errors drop, visibility improves, and your team spends month-end reviewing instead of reconciling.
*Tekion is a financial technology company, not a bank. Banking services are provided by Core Bank, Member FDIC. FDIC insurance covers only the failure of an FDIC-insured bank, and pass-through coverage is subject to certain conditions. The deposit bonus of up to 2.00% annualized is variable, depends on balance, and may change at any time. The card balance is due in full every 30 days.
*Brex LLC is a wholly owned subsidiary of Capital One, N.A. | Brex LLC 2261 Market Street STE 85844 | San Francisco, CA 94114 | Brex LLC 650 S 500W Suite 300 | Salt Lake City, UT 84101 |The Brex Mastercard® Corporate Credit Card is issued by Emigrant Bank, Fifth Third Bank N.A., or Airwallex (Netherlands) B.V. (all unaffiliated institutions) pursuant to licenses by Mastercard International Inc. The Brex Visa Commercial Card is issued by Sutton Bank (an unaffiliated institution). All loans are subject to approval, including underwriting, credit, and collateral approval, as well as availability restrictions. Nothing herein should be construed as a commitment to lend.Certain payment services are provided by Brex Payments LLC (NMLS #2035354), a Capital One company.